Who can buy a vehicle net inside the EU
The VAT-free purchase is open to businesses registered in another EU member state. That includes dealerships, trading companies, leasing providers and any other business with a valid VAT number. Whether you run a GmbH, an Italian S.r.l., a French S.A.S. or a Spanish S.L. makes no difference, as long as the number is confirmed in the European system.
Private individuals living in the EU cannot buy net. For them the destination principle only applies to new vehicles, and the tax is then due in their country of residence rather than in Germany. If you are a private buyer and want a net price, the route runs through an export to a country outside the EU. We cover that on a separate page.
- Businesses registered in another EU member state
- Valid VAT number, confirmed in the system
- Vehicle demonstrably leaves Germany
Why we do not ask for a VAT deposit
Many dealers charge a deposit equal to the VAT, which is 19 percent of the vehicle value. You only get it back once the proof of export or arrival is in. On an 80,000 euro vehicle that is 15,200 euros tied up for weeks.
We do it differently. If your documents are complete in advance and the VAT number is confirmed, we ask for no deposit. You pay the net price plus our commission from the start. That works because we build the chain of evidence before the purchase rather than after it. The effort sits with us instead of with your cash flow.
- No 19 percent of the purchase price tied up
- Net price plus commission from day one
- Condition: complete documents before the purchase
Checking the VAT number before any offer is made
Before we reserve a vehicle for you we verify your VAT identification number in the confirmation procedure. This is not only about whether the number exists, but whether it matches the company name and address you gave us. We document that qualified confirmation and file it with the purchase.
On top of that we ask for a current commercial register extract or the equivalent document in your country, plus identification of the authorised representative. It sounds like bureaucracy, and it replaces every later discussion with the tax office. Skipping this check risks having the exemption withdrawn afterwards, with the 19 percent falling due after all.
- Qualified confirmation of name and address
- Commercial register extract or equivalent
- ID copy of the authorised representative
Proof of arrival: the document everything depends on
The proof of arrival, known in German as the Gelangensnachweis, shows that the vehicle really reached the other EU country. Without it there is no exemption, no matter how clean the rest of the file looks. It states the buyer's name and address, the vehicle identification number, the place and month of receipt, and carries the buyer's signature.
When we organise the transport, a CMR consignment note with the receipt confirmation from the destination usually takes its place. If you collect the vehicle yourself we also need a power of attorney for the driver and a confirmation after arrival. We tell you in advance which variant applies to you and send the template with it.
- Arrival confirmation with the vehicle identification number
- CMR consignment note when we arrange transport
- Templates and deadlines come from us
Transport to your EU country: open, enclosed or driven
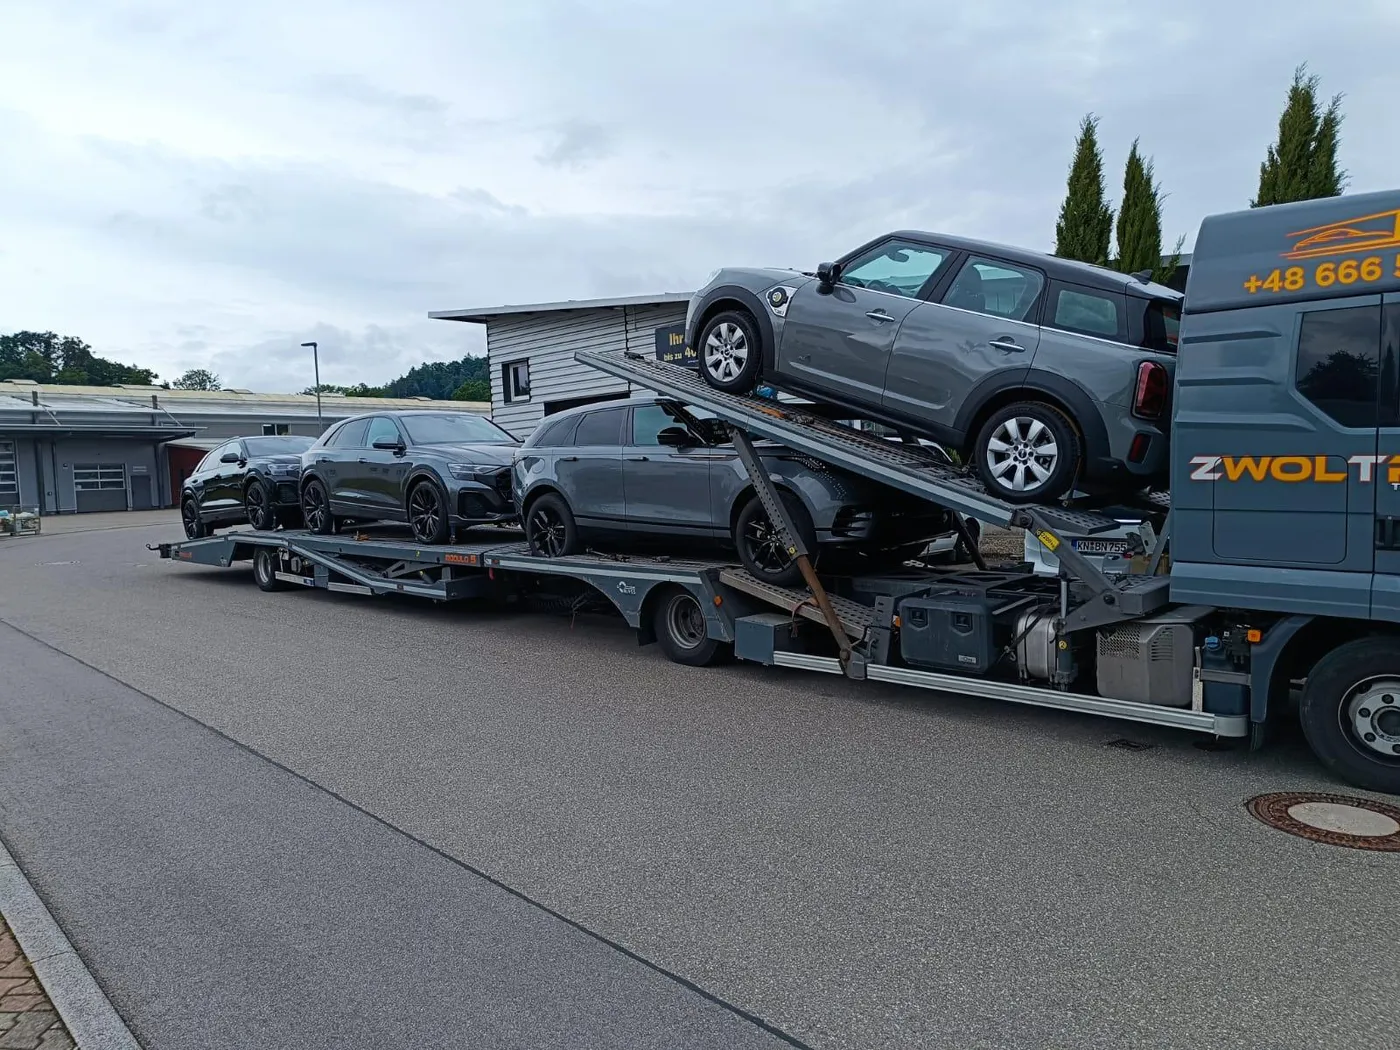
From Lake Constance, Milan, Zurich, Lyon and Vienna are within a day's reach, while Barcelona, Warsaw and Copenhagen are predictable two-day runs. Inside the EU we use open car transporters, enclosed transport for delicate or high-value vehicles, and in individual cases a transfer under the vehicle's own power.
Which option makes sense depends on the vehicle, not on price alone. A groupage transport costs less but needs a time window. An enclosed single transport costs more and protects paint and wheels. We give you both options with cost and date before you commit. There is more detail on our worldwide vehicle transport page.
- Open groupage or enclosed single transport
- Transport insurance on request
- Handover at your address in the destination country
What a net purchase means for your calculation
On an intra-community acquisition you account for the tax in your own country and deduct it as input tax in the same step, provided you are entitled to do so. What remains is the net price. The advantage over buying with German VAT is not a saving as such, it is that no money sits locked in a refund procedure for months.
We quote our commission as a fixed amount before the purchase, not as a percentage of a price that is still being negotiated. Transport comes on top, and plates and transfer if they are needed. You receive a breakdown of every item before anything becomes binding.
- Fixed commission instead of variable percentages
- All additional costs named in advance
- No fees added afterwards